Part Two of a Two-Part Series
Imagine receiving a letter informing you that your disability insurance benefits are being terminated. You’ve been receiving those payments because your medical condition prevents you from working, and you’ve come to depend on that money to pay your bills. Your disability hasn’t disappeared. Your doctor hasn’t suddenly declared you capable of returning to work. Yet the insurance company has decided that you no longer qualify.
Now what?
For people with physical disabilities, financial independence can represent years of hard work, planning, and sacrifice. We build careers, pay insurance premiums, and make decisions based on the expectation that certain protections will be there when we need them. Discovering that those protections aren’t as dependable as we believed can be frightening.
In Part One of this series, attorney Justin C. Frankel, Esq., explained why having a disability doesn’t automatically qualify someone for disability insurance benefits. We discussed preexisting conditions, occupational requirements, and the importance of documenting changes in our ability to work.
But what happens after a claim has been approved? Can an insurance company suddenly stop paying? And how much of our personal lives can insurers examine while deciding whether we deserve the benefits we’ve been receiving?
Frankel, founder of the Law Office of Justin C. Frankel, P.C., in Carle Place, New York, has spent more than two decades representing people whose disability insurance claims have been denied or terminated. For this second installment, I wanted to understand what people should know before finding themselves in a financial battle with their insurance company.
Your Benefits Were Approved. That Doesn’t Mean They’re Guaranteed.
One of the most unsettling aspects of disability insurance is that approval doesn’t necessarily mean the matter is settled.
An insurance company may continue reviewing a claim long after payments begin. It can request updated medical records, ask for additional information about your daily activities, or reassess whether you satisfy the disability definition in your policy.
And yes, benefits that were previously approved can be terminated.
For someone whose disability hasn’t improved, that decision might seem impossible to understand. If you couldn’t work six months ago and you still can’t work today, why would the insurance company suddenly reach a different conclusion?
Frankel explains that disability insurance companies evaluate claims according to the terms of the policy. A change in how the insurer interprets medical evidence, an assessment of occupational abilities, or a transition to a different disability definition can affect whether payments continue.
Some policies initially consider whether you can perform your own occupation, then later examine whether you can perform another occupation. That distinction can make an enormous difference.
Being unable to return to the career you’ve spent decades building doesn’t necessarily mean the insurer will agree that you’re unable to work in another capacity.
And that brings us to an uncomfortable reality. The insurance company may reach a conclusion about your ability to work that is very different from your doctor’s assessment.
The Letter You Cannot Afford to Ignore
If your disability insurance benefits are denied or terminated, your first reaction might be anger, disbelief, or panic. All understandable. But according to Frankel, one of the most important things you can do is pay attention to the deadline in the insurer’s letter.
Appeal deadlines matter.
Depending on the type of policy, missing one could seriously limit your ability to challenge the decision. Frankel recommends reviewing the denial or termination letter carefully, obtaining a complete copy of your insurance policy and claim file, and consulting an attorney experienced in disability insurance disputes.
Requesting documents is important, but don’t assume that asking for your claim file automatically extends your appeal deadline.
That’s a distinction worth remembering.
The claim file may contain medical reviews, vocational assessments, correspondence, and other information the insurance company relied upon when making its decision. Understanding that evidence can help identify what needs to be addressed in an appeal.
For certain employer-sponsored plans governed by the Employee Retirement Income Security Act, commonly known as ERISA, the administrative appeal process is particularly important. Evidence that isn’t properly submitted during that process may be difficult to introduce later in court.
In other words, responding to a denial isn’t simply a matter of writing an angry letter explaining why the insurance company is wrong.
You need to understand what the insurer is claiming, what evidence supports or contradicts that position, and what your policy requires.
And you need to act before the applicable deadline expires.
Apparently, Having a Life Can Be Used Against You
This part of our discussion caught my attention.
Imagine being a wheelchair user who can no longer work because of worsening pain, fatigue, or another medical condition. You attend a family celebration, go on vacation, or spend an afternoon enjoying yourself. Someone takes a photograph, and you share it on social media.
To you, it’s a photograph of a pleasant afternoon.
To an insurance investigator, it could become something else.
Frankel explains that insurers may examine social media activity, photographs, travel, hobbies, and other aspects of a claimant’s life when evaluating disability benefits. Some companies also use surveillance.
The problem is that a photograph captures a moment. It doesn’t necessarily reveal what happened before or afterward.
A person might attend a wedding and spend the following two days recovering. Someone might enjoy a vacation because family members provide assistance that isn’t visible in the photographs. A wheelchair user might participate in an activity for an hour but be unable to sustain the physical or mental demands of a full-time job.
None of those circumstances automatically establishes the ability to work.
Yet an insurer may interpret isolated activities as inconsistent with someone’s reported limitations.
I find that particularly troubling because people with physical disabilities already encounter assumptions about what we can and cannot do. We shouldn’t have to choose between enjoying our lives and being believed about our limitations.
Frankel’s guidance isn’t to stop participating in life or disappear from social media. It’s to be accurate and consistent when describing your activities and limitations.
If an activity requires assistance, causes significant pain, or results in days of recovery, those details matter. They provide context that a photograph cannot.
There’s a substantial difference between being able to do something occasionally and being able to perform a job reliably, day after day.
And frankly, enjoying yourself shouldn’t be treated as evidence that you’re suddenly capable of returning to work.
Not All Disability Benefits Follow the Same Rules
When people talk about disability benefits, they often lump everything together. But private disability insurance, employer-sponsored coverage, and Social Security Disability Insurance aren’t interchangeable.
Frankel emphasizes that understanding which type of coverage you have is essential because the rules governing claims and appeals can differ considerably.
An individually purchased disability insurance policy is generally governed by its contract and applicable state law. Many employer-sponsored disability plans, particularly those offered by private-sector employers, are governed by ERISA.
Social Security Disability Insurance, or SSDI, is a federal program administered by the Social Security Administration. Its eligibility standards and appeal procedures are different from those of private insurance companies.
You might qualify for SSDI but not meet the definition of disability under a private policy. The reverse can also happen.
Approval under one program doesn’t automatically establish eligibility under another.
Some private disability insurance policies also coordinate benefits with Social Security, which can affect the amount the private insurer pays.
That’s why knowing the name of your insurance company isn’t enough. You need to know what kind of policy you have, what it covers, and which rules apply when something goes wrong.
Can You Afford an Attorney When You’ve Lost Your Income?
There’s another question that deserves attention.
What happens when someone needs legal representation precisely because the insurance company has stopped providing the income that person depends on?
Hiring an attorney can sound financially impossible when you’re already worried about paying the mortgage, rent, utilities, or other living expenses.
Frankel explains that disability insurance attorneys may offer different fee arrangements. Some provide free initial consultations, while representation may involve contingency fees, hourly billing, or another arrangement depending on the case.
The important thing is to understand the financial agreement before hiring anyone.
Ask how the attorney will be paid, whether fees apply to recovered past-due benefits, whether future benefits are included in the calculation, and what additional expenses you might be responsible for.
Medical experts, vocational specialists, and other professionals may become involved in a disability insurance dispute. Those costs should be discussed as well.
Don’t assume every attorney uses the same fee structure, and don’t assume that seeking legal advice automatically means paying a substantial amount upfront. A consultation can help you understand your options before making a financial commitment.
It may also help you avoid mistakes that become much more expensive later.
Protecting Yourself Before You Need to File a Claim
One of the strongest messages I took from Frankel’s responses is that understanding your insurance coverage shouldn’t begin when you become unable to work.
By then, some of the most important decisions may already have been made.
If you have disability insurance through your employer or a policy you’ve purchased yourself, do you know what it actually covers?
Do you know how long benefits can last? Whether partial disability is covered? What happens if your hours are reduced or you change employers? Whether another source of income could reduce your payments?
What about early retirement?
These aren’t particularly exciting questions. I can think of far more enjoyable ways to spend an afternoon than reading an insurance policy. But the answers could have a significant impact on your financial future.
Frankel encourages policyholders to understand the definition of disability, exclusions, benefit duration, and provisions that could affect eligibility or payments.
For people with lifelong physical disabilities, this deserves particular attention. Our circumstances can change even when the underlying disability has been present since birth.
A person who has worked successfully for 20 or 30 years may eventually experience additional medical complications, worsening fatigue, or physical limitations that make continuing in the same occupation impossible.
The fact that we previously found ways to work doesn’t mean our bodies will always cooperate with our determination.
And the financial consequences of losing employment can be substantial.
Insurance is supposed to provide protection against that possibility. But protection is only useful when we understand what we’ve purchased and what we must do to maintain our rights under the policy.
Financial Independence Shouldn’t Depend on Guesswork
I believe in financial independence. I also believe that people with physical disabilities deserve the same opportunity to build careers, earn a living, and prepare for their futures as anyone else.
But independence doesn’t mean pretending we’ll never need help, financial or otherwise.
Sometimes protecting ourselves means asking difficult questions before there’s a problem. Sometimes it means keeping better records, reading documents we’d rather ignore, or seeking professional advice when an insurance company makes a decision that threatens our income.
And sometimes it means recognizing that having paid for disability insurance doesn’t guarantee the company will agree to pay a claim.
Throughout this two-part series, Frankel has explained something I think every working person with a physical disability should understand: disability insurance is governed by contractual definitions, documentation requirements, and legal procedures that may not reflect how we experience our disabilities.
That doesn’t mean we should abandon the idea of protecting our income. It means we should understand the protection we’re counting on.
After all, we’ve spent enough of our lives dealing with obstacles we didn’t create. We shouldn’t have to discover the limitations of our financial safety net only after we need it.
About Justin C. Frankel
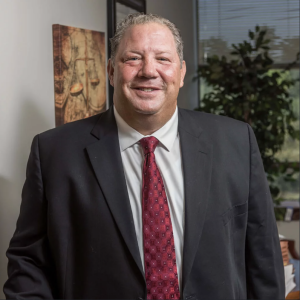
Justin C. Frankel, Esq., is the founder of the Law Office of Justin C. Frankel, P.C., in Carle Place, New York. His practice focuses on private disability insurance claims and disputes. His responses for this two-part series were provided in writing, reviewed, and approved by him for publication.
This article provides general information and does not constitute legal advice. Disability insurance rights, appeal deadlines, and coverage requirements depend on the individual policy and applicable law.
Stay Connected With Audacity Magazine
Financial independence matters, and so does having access to information that helps us protect it. That’s why Audacity Magazine continues to bring you conversations about the issues that affect our lives as people with physical disabilities.
Subscribe to the Audacity Magazine newsletter for more stories, conversations, and information that matter to our community.
And if you appreciate independent journalism that keeps people with physical disabilities at the center of the conversation, buy me a coffee. Your support helps keep Audacity Magazine going!