Part One of a Two-Part Series
You’ve worked for years, perhaps decades. You’ve paid your bills, built a career, and contributed to your retirement. If you’ve lived with a physical disability since childhood, you’ve probably spent a good portion of your life figuring out how to do things your way. Maybe you’ve made adjustments to your work schedule, invested in adaptive equipment, or found ways to manage pain and fatigue without allowing either to interfere with your responsibilities.
Then something changes. Your disability progresses, you develop another medical condition, or your body simply cannot keep up with the demands of your job anymore. You have disability insurance, so at least there’s some financial protection, right?
Not necessarily.
Having a disability and qualifying for disability insurance benefits are two very different things. And if you think your medical records, your doctor’s opinion, and years of paying insurance premiums guarantee that you’ll receive benefits, you might be in for an unpleasant surprise.
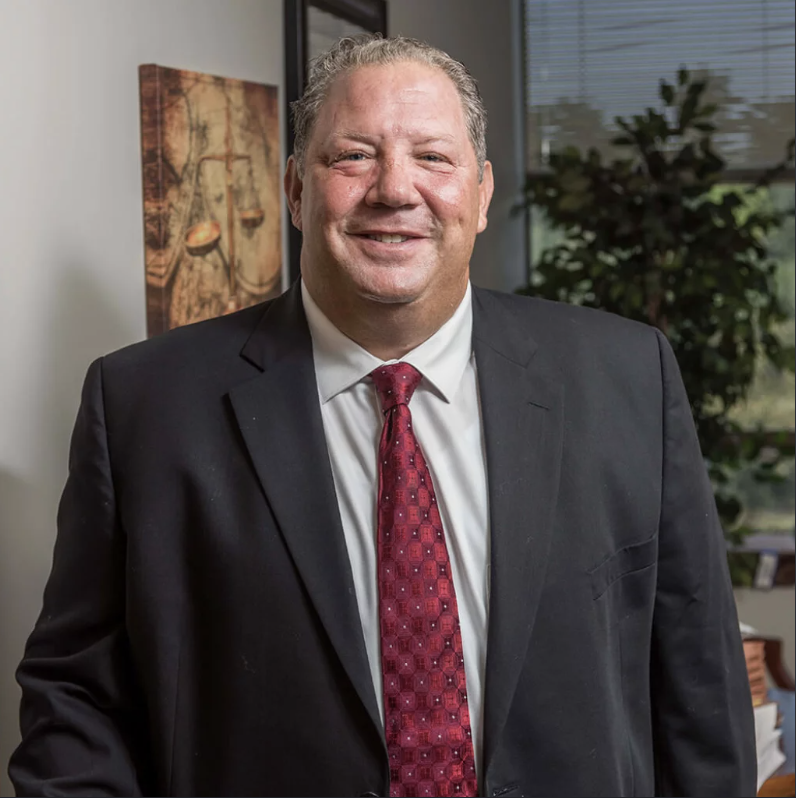
Justin C. Frankel, Esq., founder of the Law Office of Justin C. Frankel, P.C., in Carle Place, New York, has spent more than two decades representing people whose disability insurance benefits have been denied or terminated. I saw an opportunity to ask questions that matter to AudacityMagazine.com’s readers, particularly those of us who have lived with physical disabilities for most or all of our lives.
After all, many of us have spent years proving what we can do. But what happens when our circumstances change and we need the insurance coverage we’ve been paying for?
Your Doctor Says You’re Disabled. Your Insurance Company Might Disagree.
One of the first things Frankel wants policyholders to understand is that disability insurance is a contract, not simply a medical determination.
“I wish every policyholder understood that a disability insurance claim is not simply a medical issue. It is a contractual claim being evaluated by a company that has a financial interest in the outcome,” he explains.
Your doctor is concerned with diagnosing your condition, treating your symptoms, and helping you function as well as possible. The insurance company is determining whether your circumstances meet the definition of disability written into your policy.
Those two perspectives don’t always agree.
A medical diagnosis confirms that a condition exists, but disability insurance generally requires evidence showing how that condition prevents you from performing the duties of your occupation. Depending on your policy, the insurer may also consider whether you could perform another occupation suited to your education, training, or experience.
Frankel uses degenerative disc disease as an example. An MRI might confirm the diagnosis, but an insurance company could still ask whether the person can sit for extended periods, maintain productivity throughout an eight-hour workday, attend work consistently, or concentrate despite pain.
The same questions can arise with multiple sclerosis, Parkinson’s disease, traumatic brain injury, Long COVID, chronic fatigue syndrome, fibromyalgia, depression, and other conditions where symptoms may interfere with work even when diagnostic testing doesn’t tell the entire story.
In other words, the insurance company isn’t necessarily disputing that you have a medical condition. It may be disputing whether that condition prevents you from working under the terms of your policy.
And there’s something else worth knowing. Approval isn’t necessarily the end of the process.
Frankel explains that insurers may review claims long after benefits begin. They can request updated medical records, require physician statements, commission medical reviews, conduct surveillance, and reconsider whether someone continues to meet the policy’s definition of disability.
Imagine receiving benefits for years and then having to prove your eligibility all over again.
Paying premiums doesn’t guarantee that benefits will be approved or continue indefinitely. The evidence must satisfy the policy’s requirements, and those requirements deserve attention long before anyone files a claim.
What If You’ve Been Disabled Your Entire Life?
Many of our readers weren’t suddenly introduced to disability as adults. We’ve been living with physical disabilities since childhood, sometimes since birth. We’ve gone to school, pursued careers, raised families, and learned how to navigate workplaces that weren’t necessarily designed with us in mind.
So what happens when someone with a preexisting disability wants to purchase disability insurance?
According to Frankel, the answer depends on the policy.
Individual disability insurance companies often review medical histories before deciding whether to provide coverage. An insurer might offer coverage without restrictions, exclude certain conditions, charge a higher premium, or decline coverage altogether.
Sometimes an exclusion applies to a particular medical condition or body system while the rest of the policy remains available.
Employer-sponsored insurance may operate differently. Medical underwriting can be limited or eliminated during enrollment, but group policies may still contain preexisting-condition limitations. Those restrictions can affect benefits when a disability arises shortly after coverage begins.
The dates matter, too. When you received treatment, when a condition was diagnosed, when coverage began, and when your ability to work changed can all affect a claim.
Frankel recommends reviewing the actual policy rather than relying on an attractive brochure or a brief explanation during employee enrollment.
Before enrolling, find out whether your existing condition is covered, whether any exclusions apply, and when coverage becomes effective. Ask about requirements to be actively working, what happens if you change employers, and whether reducing your work hours could affect eligibility.
It’s also worth checking whether previous coverage satisfies any waiting periods and whether the policy contains limitations involving mental health conditions or specific medical diagnoses.
These aren’t the most exciting things to read. I understand that. Insurance documents aren’t exactly what I reach for when I want to relax with a cup of coffee. But neither is discovering that a policy you thought covered you contains an exclusion you never knew existed.
And don’t assume the summary your employer hands you contains every important detail.
“The governing policy language is what ultimately controls,” Frankel emphasizes.
You Worked With Your Disability Before. Why Can’t You Work Now?
Imagine spending 20 or 30 years demonstrating that having a physical disability doesn’t prevent you from being a successful employee. You show up, meet expectations, and build a career. You might even work harder than your colleagues to accomplish the same responsibilities.
Then your condition worsens.
Perhaps you develop chronic pain, lose some mobility, experience additional medical complications, or find that tasks you’ve performed for years now require considerably more effort.
You file a disability insurance claim, only to encounter an argument you never expected.
“You worked with this condition before, so why can’t you continue working now?”
Frankel says insurers sometimes use that reasoning when evaluating claims involving longstanding disabilities.
Think about that for a moment. Your years of employment, which demonstrate your ability to contribute professionally, can become part of an argument against your claim when your circumstances change.
Frankel points out that such reasoning can overlook the ways disabilities evolve.
A wheelchair user who has relied on their arms for decades might develop severe shoulder degeneration. Someone with cerebral palsy might experience worsening mobility with age. A person born with a disability could develop additional medical conditions that affect their ability to work.
These changes matter, but they must be documented.
The important issue becomes what has changed between the years when someone could perform their job and the point when they could no longer do so.
Medical records, physician opinions, vocational evidence, and personal testimony can help establish that difference.
Frankel also recognizes that many people with disabilities maintain careers through accommodations, adaptive equipment, modified schedules, assistance from others, and considerable determination.
But the ability to work successfully in the past doesn’t automatically mean someone can continue doing so under different physical circumstances.
“A successful work history should not be viewed as evidence against a disability claim,” he says.
Unfortunately, that doesn’t mean an insurance company will automatically see it the same way.
Your Job Title Doesn’t Tell the Whole Story
There’s another misconception worth addressing: the idea that certain jobs are easy because they don’t involve much physical activity.
An insurance company might classify an executive, attorney, accountant, engineer, physician, or technology professional as performing sedentary work.
But sitting at a desk doesn’t mean a job requires little effort. Consider the concentration involved in making important decisions, managing employees, solving problems, communicating with clients, meeting deadlines, or maintaining productivity throughout the day.
Frankel explains that insurance companies sometimes overlook these demands when evaluating occupations.
Two people with the same medical diagnosis could receive different disability insurance decisions because their jobs require different abilities.
For example, a hand injury might prevent a surgeon from operating but have less impact on someone whose occupation doesn’t require that level of manual precision. Meanwhile, someone whose work depends on concentration and complex decision-making might be unable to perform their duties because of cognitive impairment, even if their physical abilities remain largely unchanged.
The policy’s definition of disability matters here, too.
An “own occupation” policy generally considers whether you can perform your particular occupation. An “any occupation” provision uses a broader standard, considering other work for which you may be reasonably qualified.
That distinction can make an enormous difference when an insurance company evaluates your claim.
It’s another reason to know what your policy actually says rather than assuming that disability insurance means the same thing for everyone.
Your Medical Records Need to Tell More Than Half the Story
Most of us understand the importance of keeping medical records. But Frankel explains that having a thick medical file isn’t necessarily the same as having strong evidence for a disability insurance claim.
Medical records document diagnoses, symptoms, treatment, and clinical findings. Physician statements can explain how those conditions affect someone’s ability to function. Personal documentation adds another layer by showing what those limitations mean in everyday life and at work.
And people with longstanding physical disabilities may face an additional challenge.
We’ve often spent years adapting to our circumstances. We learn to compensate, adjust our routines, and manage activities without necessarily explaining every difficulty to someone else.
Frankel says that can lead people to underreport how much their conditions actually affect them during medical appointments.
Maybe you’ve become accustomed to needing extra time to complete a task. Perhaps you don’t mention how exhausted you feel after work because fatigue has become part of your routine. Or you receive assistance with certain activities but don’t consider it worth mentioning because you’ve always had that assistance.
Those details can matter when an insurer is evaluating your ability to work.
Frankel recommends being specific and accurate with medical providers. Explain what assistance you need, how long activities take, how frequently you need breaks, and what happens afterward.
He also suggests keeping records of your job responsibilities, performance expectations, workplace accommodations, schedule changes, missed work, and difficulties with concentration or productivity.
Even fatigue after work and assistance needed at home or on the job may help explain your circumstances. The purpose isn’t to exaggerate limitations or portray yourself as less capable than you are. It’s to make sure your records accurately reflect what you’re experiencing.
After all, an insurance company reviewing your file doesn’t see everything that happens between medical appointments.
Don’t Wait Until Something Goes Wrong
One message comes through repeatedly in Frankel’s responses: preparation matters.
Understand your coverage. Keep copies of your policy, correspondence, medical records, and important forms. Pay attention to deadlines. Document changes in your condition and how those changes affect your work.
And remember that having disability insurance isn’t necessarily the same as having the protection you expect.
I find that particularly important for people with physical disabilities who have spent years building careers and financial independence. We shouldn’t have to discover the limitations of our insurance coverage at the very moment we’re counting on it.
Frankel’s advice is to treat the claims process seriously from the beginning, even when everything appears to be going smoothly.
Because when an insurance company questions your eligibility, what you’ve documented may become just as important as what you’ve experienced.
And that brings us to another concern.
What happens when the insurance company has already approved your benefits and suddenly decides to stop paying? What if a photograph from your vacation, a social media post, or an ordinary afternoon out becomes part of the evidence used to challenge your claim?
That’s where Part Two of our conversation with Justin C. Frankel begins.
Coming in Part Two: What to do when disability insurance benefits are denied or terminated, how insurers may use social media and surveillance, what legal representation could cost, and the steps that may help protect your financial independence.
Justin C. Frankel, Esq., is the founder of the Law Office of Justin C. Frankel, P.C., in Carle Place, New York. His practice focuses on private disability insurance claims and disputes. His responses were provided in writing, reviewed, and approved by him for publication.
This article provides general information and does not constitute legal advice. Disability insurance rights and requirements depend on the individual policy and applicable law.
Stay Connected With Audacity Magazine
Living with a physical disability comes with enough surprises. Understanding your rights and your options shouldn’t have to be one of them.
Subscribe to the Audacity Magazine newsletter for more conversations, stories, and information that matter to people with physical disabilities.
And if you appreciate independent journalism that puts our community first, you can buy me a coffee. Every cup helps keep Audacity Magazine going!